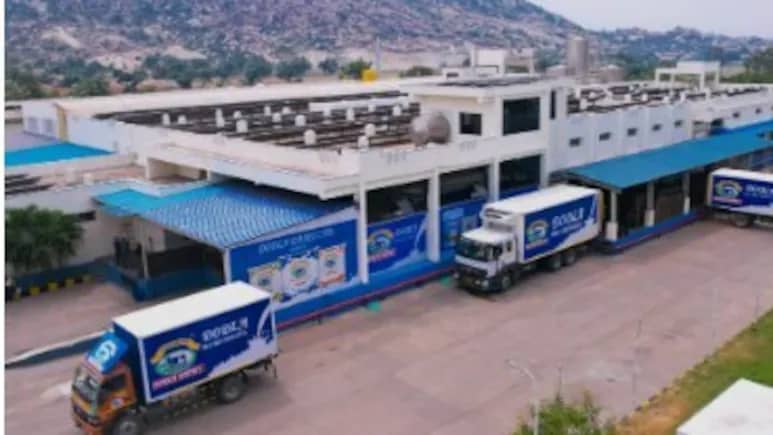
Strong demand for dairy products and multiple capacity-expansion initiatives are expected to support Dodla Dairy’s medium-term growth, according to brokerage Systematix Institutional Equities.
Systematix has maintained its Buy rating on Dodla Dairy and an unchanged target price of ₹1,295 per share, valuing the company at 24 times its June 2028 estimated earnings per share. The target represented a potential 23% upside from the ₹1,048 market price cited in the report. These are the brokerage’s estimates and valuation views, not a guaranteed return.
The brokerage has kept its FY27E–FY29E estimates unchanged and projects a 13% revenue CAGR and 24% profit-after-tax CAGR between FY26 and FY29. It expects Dodla to maintain low-to-mid teens revenue growth, led by its India value-added products (VAP) business and operations in Africa.
Capacity Expansion and Value-Added Dairy
Systematix identified several medium-term growth drivers for Dodla Dairy, including capacity expansion in Maharashtra and Uganda and the continued development of Osam, which is expected to strengthen the company’s presence in eastern India.
The brokerage estimates India and Africa sales to grow at CAGRs of approximately 12% and 22%, respectively, between FY26 and FY29. Value-added products are expected to grow at around 20%, supported by incremental volumes from new capacity and the addition of Osam.
Milk Costs Remain a Key Variable
Sharp milk-price inflation has affected Dodla’s operating profitability over the past two quarters, according to Systematix. However, the brokerage noted that operating profit margin improved by 40 basis points quarter-on-quarter in Q1 FY27, while management has guided for another improvement in Q2 FY27.
Systematix expects margins to improve gradually during FY27 as price increases flow through and the company's product mix shifts further towards value-added products and Africa operations. It models a modest operating-margin decline in FY27E, followed by margin expansion in subsequent periods.
The brokerage also highlighted the possibility of constrained and volatile milk supplies in the near term, which could keep procurement costs elevated. It believes Dodla’s pricing capabilities, inventory management, procurement network and supply-chain infrastructure will be important in navigating these conditions.
For the broader dairy industry, the report highlights the continuing importance of value-added products, geographic expansion and procurement efficiency as companies manage volatile milk costs while responding to sustained consumer demand.
Source: Dairynews7x7 25 Sep, 2026 Read full story here
#DairyIndustry #DodlaDairy #ValueAddedDairy #DairyMarket #MilkProcurement #DairyBusiness #DairyNews7x7