After a whole year of pandemic and lockdowns across the globe, the view of the future is clearer and more hopeful than it has been for months for the world dairy markets. By mid-year, there should be a palpable return to familiar consumer patterns. It won’t be immediate, and certainly not smooth, but on balance, it should be positive for dairy markets.
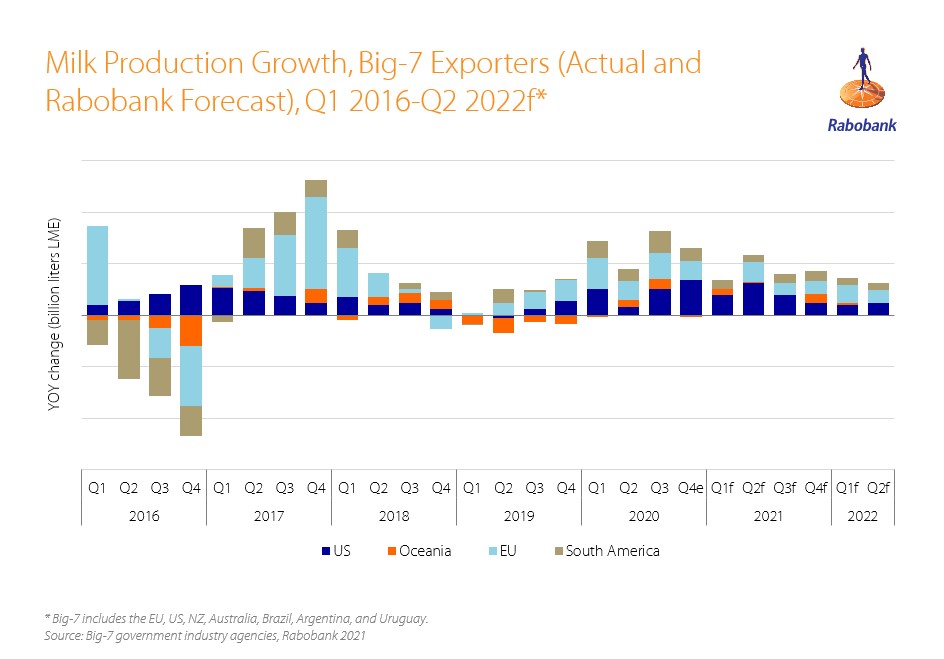
Rabobank forecasts a 1.1% increase in milk production across the Big-7 dairy-producing regions in 2021. This is a decrease compared to the 1.6% year-on-year increase in 2020 and represents a modest tightening of supply, which should help support markets as demand settles into post-vaccine balance.
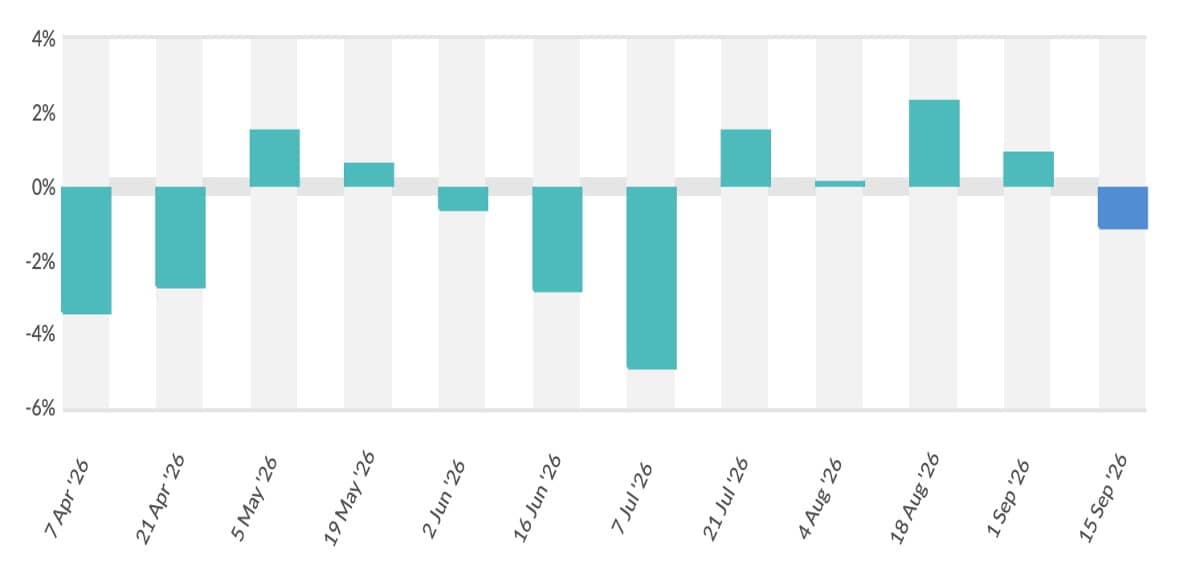
“China’s near-term import demand is elevated, but is expected to slow in the second half of the year. High domestic milk prices are driving interest in expanding domestic milk production, which could reduce import needs in the future,” according to Ben Laine, analyst – dairy at Rabobank. The high milk prices favoured imported whole milk powder (WMP) early in the year, but that demand could see a pause following a recent spike in Oceania prices. Milk prices in China have likely reached a peak and will begin to soften from here.
Never miss an important dairy update
Follow DairyNews7x7 on Google to get live milk prices, policy alerts, and daily headlines directly in your feed.