Annual global milk supply forecast to expand by two percent in 2026
By•
Annual global milk supply forecast to expand by two percent in 2026

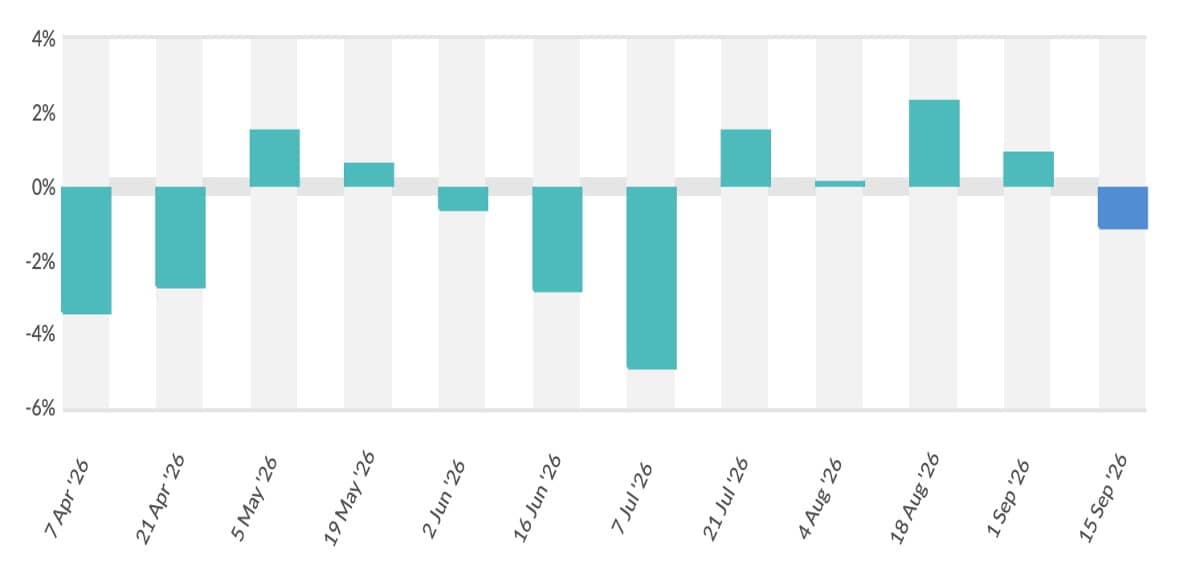
Annual global milk supplies are now forecast to expand by 2.2 percent across 2026, propelled by resilient output across the world’s primary dairy exporting regions, according to the October 2026 Market Report released by Irish dairy cooperative exporter Ornua. The upward projection reflects robust raw milk collections that have largely outpaced earlier seasonal disruptions, demonstrating underlying biological and operational momentum across key production sheds. Looking ahead, Ornua projects global volume expansion to moderate to approximately 1.0 percent in 2027. However, market analysts emphasize that the eventual development and intensity of the El Niño weather pattern introduces substantial climatic uncertainty, posing potential volatility for Southern Hemisphere pasture growth and global feed availability over the coming production cycles.

In the European Union, raw milk collections have shown surprising structural resilience despite localized weather headwinds. According to the report, EU milk production expanded by 1.1 percent in September, reflecting a seasonal deceleration compared to the 2.5 percent growth recorded in August. Despite pronounced drought conditions affecting central and western continental milk sheds during late summer, collection volumes proved better than anticipated, particularly in key processing powerhouses France and Germany. This stronger-than-expected throughput has prompted analysts to revise the annual EU production growth forecast back to pre-drought expectations of +1.9 percent. While European farmgate margins continue to navigate elevated regulatory compliance overheads and feed costs, sustained milk collection indicates that herd productivity gains have helped buffer against localized climatic stress.

Beyond the European continent, key exporting competitors in North America and Oceania have reinforced the global volume expansion. In the United States, commercial milk output continues to expand at a steady pace, underpinned by a modest expansion in cow numbers, increasing milk component densities, and new regional processing capacity that incentivizes farm-level throughput. Concurrently, New Zealand opened the 2026/27 production season with exceptional early-spring momentum, registering monthly collection records supported by favorable seasonal pasture conditions, expanded autumn calving, and extended winter milking routines that help smooth seasonal intake curves. In Australia, raw milk deliveries have similarly exceeded conservative industry baselines, adding incremental exportable surplus into Pacific Rim supply chains and contributing to the aggregate 2.2 percent global expansion.

From an industrial processing and commodity balancing perspective, expanding raw milk volumes exert direct influence over product manufacturing allocations and wholesale price discovery. With higher milk solids entering commercial intake docks, primary dairy manufacturers across Europe and the Americas have channeled surplus volumes into cheese vats and milk drying towers. While international demand for specialized dairy proteins and functional food ingredients remains steady, rising baseline milk supplies have moderated spot-market pricing across bulk commodities, including skim milk powder and whole milk powder. Managing inventory carryover and balancing operating schedules across continuous manufacturing facilities will be critical for regional cooperatives seeking to prevent margin erosion during the impending production peaks.


Never miss an important dairy update

Follow DairyNews7x7 on Google to get live milk prices, policy alerts, and daily headlines directly in your feed.